
Wealth clients of any significant size spread their assets across several custodians, often across borders, and every bank reports in its own format on its own schedule. Turning that scatter into one coherent client picture is the baseline, and the point where manual setups lose the week. Every statement gets pulled by hand; currencies get lined up, and then the real grind starts reconciling where the banks overlap, before a single report can go out.
Multi-bank reporting that works takes that off the team. Good software aggregates holdings across custodians and banks into one view, keeps it current, and generates client reporting from that single source. Once the data lives in one place, month-end stops being a fire drill, and the numbers stop depending on who did the copying. For a regulated wealth team, that single source is also what makes the reporting defensible later, because every figure traces back to the same place.
The harder question is compliance, and it is where generic tools quietly fall short. For a regulated wealth team, compliance is a daily job: know-your-customer (KYC) checks on every client, suitability and investor-protection checks on advice, anti-money laundering (AML) screening that actually has to happen, and a documented trail an auditor can follow without a scavenger hunt.
What sets the right software apart here is whether that work sits inside the daily workflow. When KYC, investor protection, and AML are built into the platform, the documentation builds up,
like a byproduct of normal work, so the suitability trail behind that 18-month-old decision is already there when the auditor asks. When compliance lives in separate tools and spreadsheets, it has to be reconstructed under pressure, and reconstruction is exactly when things slip through.
Multi-bank reporting and compliance only stay reliable if the software connects to the rest of how a wealth team works. Client data, portfolios, and the advisory relationship belong in the same system, so no one is assembling a client’s view from three tools before every meeting. A platform that integrates CRM, reporting, and compliance on one data set keeps the picture consistent as the book grows. One that does not turn every new client and every new regulation into another manual seam.
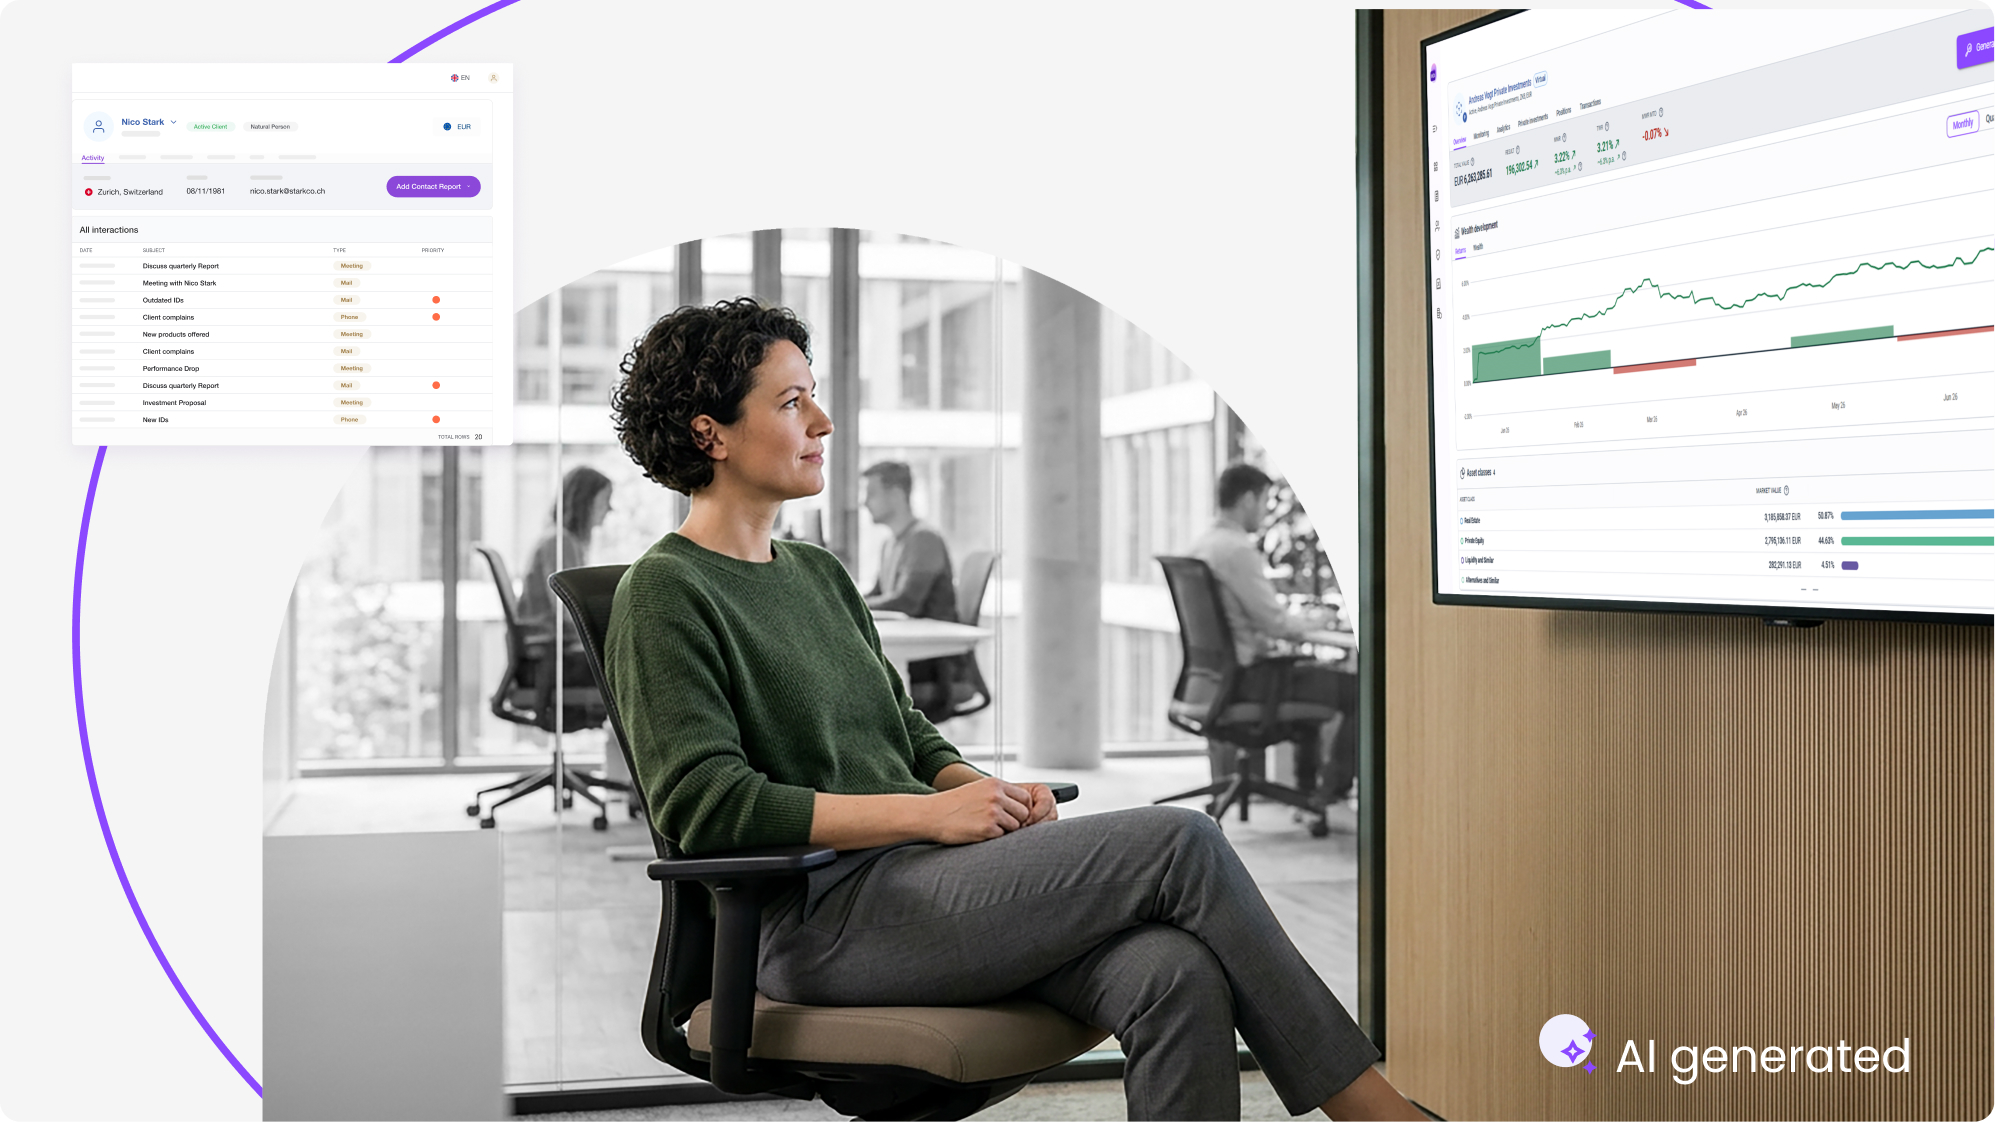
etops Wealth Discovery was built for exactly this kind of regulated wealth work. It consolidates a client’s full wealth, liquid and illiquid, across custodians and banks into one 360-degree view, with reporting that can be generated dynamically in multiple languages and currencies from that single source.
On the compliance side, it includes regulatory modules for KYC, AML, and investor protection, so the checks and their documentation sit on the same platform as the client data. KYC captures the client’s financial situation and source of wealth; investor protection runs through an integrated risk-profiling service, and AML screening covers politically exposed person (PEP) and sanctions checks. Integrated CRM and client lifecycle management keep the advisory relationship on the same data set as the portfolio and the reporting. The suitability trail and the client report come from the same source the advice was based on.
For a regulated wealth management team, software proves its worth on the day someone asks it to back something up. Multi-bank reporting that consolidates the whole client picture, compliance that documents itself as the work happens, and integration that keeps the two consistent are what hold up under that pressure. The question worth putting to any vendor is a plain one: when the auditor calls, how long does the answer take?
See how etops Wealth Discovery keeps client data consolidated and compliance documented, so the answer is ready before the auditor asks.
From newsletter sign-up to a personal demo – we look forward to hearing from you!